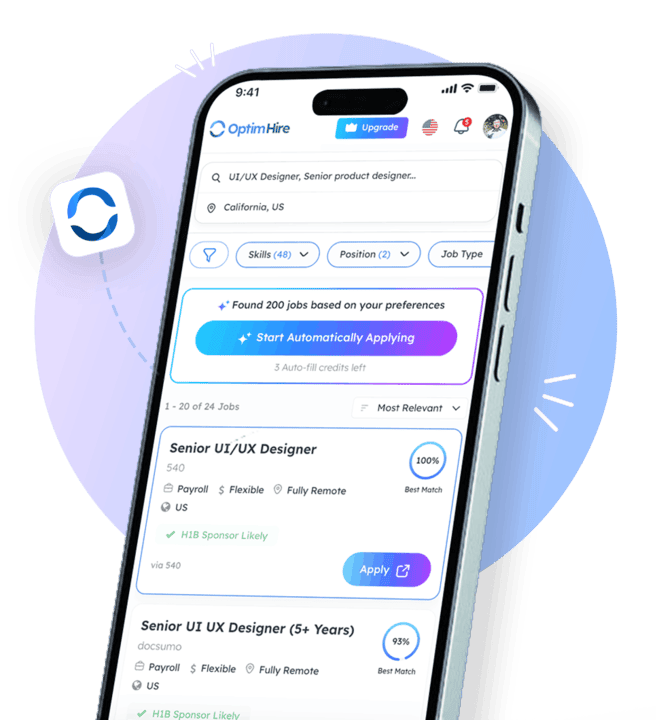
 We're excited to introduce the all new OptimHire Mobile App

OptimHire’s Job Auto-Applier that will automatically apply to jobs at 300,000+ Companies.
Quantitative Developer
Location: Iselin, New Jersey - Hybrid - 3 days a week onsite
Contract Only ($65 W2)
Interview Process: 2 rounds- 2nd round in person (onsite Interview)
Your Primary Responsibilities:
* Research and prototype risk model for newly issued ETFs.
* Extend the scope for the Hybrid VaR as a benchmark for existing VaR methodology.
* Assist the NSCC MTM passthrough effort.
* Facilitate model specification and communication with stakeholders such as Market Risk, and Risk Technology team.
Qualifications:
* 5 years of experience in financial market risk management and quantitative modeling
* Master’s degree in quantitative disciplines
* Proficient in SQL, any other high level programming languages, such as R, Python, Matlab, is a plus
* Hands on experience on developing complex financial models.
* Solid equity production knowledge, especially ETFs
* Detail oriented and team player.
Financial Analysts
Sales Analyst
Technology Analyst
Procurement Analyst
Treasury Analyst
Financial Modeling - 5 years
Risk Modelling - 5 years
ETF - 3 years
quantitative - 5 years
IT Services and Staffing Company
 Get the OptimHire App
Search smarter, apply faster, and track application on the go with the OptimHire App.

AI Powered
Job Search

Access to
10M Jobs

Auto-Apply
to Job

AI Powered
Custom Resumes


 Refer & Earn